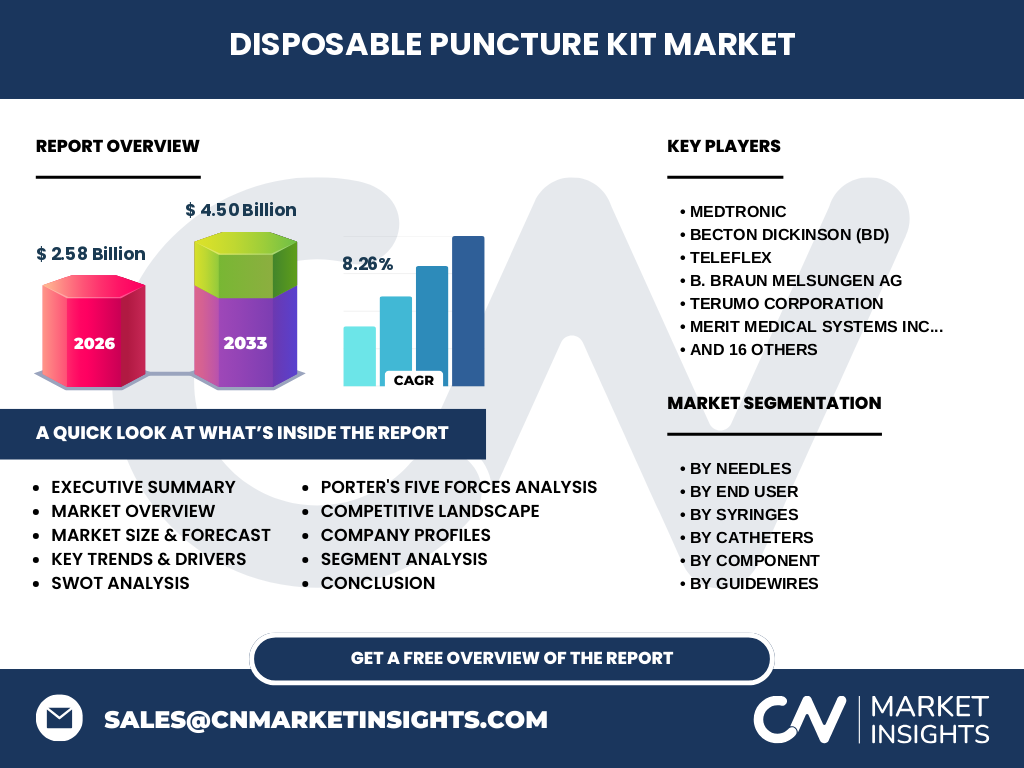
Market overview of the Disposable Puncture Kit Market
Our analysis indicates that the Disposable Puncture Kit Market represents a vital segment in clinical healthcare, valued at 2.58 Billion in 2026. This sector encompasses pre-packaged sterile procedure trays—integrating specialized components like hypodermic needles, vascular access kits, and antiseptic solutions—designed to minimize nosocomial infection risks and streamline clinical workflows across acute and ambulatory care settings globally.
Structural Growth Drivers and Market Restraints
The data suggests that the surge in minimally invasive procedures acts as a primary market catalyst, while stringent FDA and EU MDR compliance hurdles represent notable restraints. Supply chain vulnerabilities regarding medical-grade polymers and specialized metals like stainless steel for biopsy needles further challenge manufacturing margins, demanding robust logistical strategies from industry participants.
Emerging Trends in the Disposable Puncture Kit Industry
A definitive shift toward safety-engineered devices is reshaping product pipelines. Healthcare providers increasingly mandate kits equipped with safety syringes, retractable hypodermic needles, and hydrophilic guidewires to protect staff from needlestick injuries. Concurrently, the integration of advanced chlorhexidine antiseptic supplies within custom lumbar puncture trays reflects heightened sterility standards.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic caused severe supply chain disruptions and delayed elective surgeries, temporarily stalling market momentum. However, our research reveals that the post-pandemic recovery trajectory has been exceptionally robust, fueled by accelerated hospital procurement of sterile single-use aspiration puncture kits and enhanced infection control protocols designed to manage acute respiratory and surgical backlogs.
Competitive Benchmarking and Market Concentration
Industry leadership is heavily consolidated among multinational giants like Medtronic, Becton Dickinson (BD), and B. Braun Melsungen AG. These major players leverage extensive global distribution networks and robust direct sales channels to dominate hospital accounts. Meanwhile, specialized innovators such as Cook Medical and Merit Medical Systems Inc. focus on high-margin proprietary catheter and guidewire integrations.
Executive Summary of Key Research Findings
Our comprehensive evaluation highlights a projected market size reaching 4.50 Billion by 2033, expanding at a notable CAGR of 8.26% from 2027. This expansion is underpinned by rising chronic disease prevalence, technological refinements in biopsy and vascular access kits, and a structural migration of surgical procedures toward ambulatory centers.
Market Forecast for the Disposable Puncture Kit Market (2027 to 2033)
Based on our predictive macroeconomic modeling, the market will scale from its 2026 baseline of 2.58 Billion to 4.50 Billion by 2033. Achieving an 8.26% CAGR throughout this forecast window, revenue expansion will be heavily propelled by escalating demand for specialized biopsy puncture kits and advanced central venous catheter insertions worldwide.
Segmentation Analysis Across Product Lines and End Users
Market segmentation spans across product types, needle variants, syringes, catheters, and end users. Hospital systems command the largest share among end users due to high patient volumes, whereas ambulatory surgical centers represent the fastest-growing segment. Component-wise, the inclusion of specialized guidewires, surgical drapes, and antiseptic solutions dictates overall kit pricing power.
Regional Market Analysis and Geographic Performance
Geographic distribution exhibits strong regional variance, with North America leading global consumption due to advanced healthcare infrastructure. Europe follows closely, bound by stringent EMA regulatory frameworks. Meanwhile, Asia-Pacific emerges as the most lucrative regional pocket, driven by expanding healthcare expenditure in emerging economies and robust manufacturing hubs in China and India.
In-Depth Regional Review of High-Growth Territories
The Asia-Pacific sector demonstrates exceptional growth velocity, propelled by government-backed healthcare modernization initiatives in localized markets. Conversely, North America maintains revenue dominance through entrenched reimbursement frameworks that favor single-use prefilled syringes and sterile procedure trays, effectively minimizing cross-contamination liabilities in high-throughput urban hospital networks.
Company Profiles and Strategic Positioning
Strategic positioning varies significantly across key market participants. Terumo Corporation and Teleflex prioritize advanced vascular access technologies, whereas Argon Medical Devices Inc. and Pajunk GmbH Medizintechnologie specialize in targeted regional anesthesia and biopsy solutions. Regional players like Romsons Scientific And Surgical Industries capture cost-sensitive markets with high-volume standard puncture components.
Porter's Five Forces Analysis of Competitive Intensity
The threat of new entrants remains low due to formidable regulatory barriers, capital-intensive sterilization infrastructure, and established brand loyalty. However, bargaining power of buyers is moderate-to-high, as large Group Purchasing Organizations (GPOs) aggressively negotiate pricing for commodity items like standard syringes and alcohol swabs within institutional healthcare contracts.
SWOT Analysis of the Disposable Puncture Kit Sector
Strengths lie in high product standardization and critical clinical necessity. Weaknesses involve vulnerability to raw material price fluctuations. Opportunities abound in emerging market expansion for specialized vascular access kits, while threats center on stringent regulatory compliance delays and intensifying price competition from localized generic manufacturers.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with polymer and specialty steel suppliers, progressing to specialized device manufacturers who assemble comprehensive kits. Distribution relies heavily on specialized wholesalers and direct hospital sales. End-user utilization within sterile environments ensures strict traceability, turning logistics and packaging integrity into critical success factors for profitability.
Investment Insights and High-Potential Growth Areas
Investors should target manufacturers specializing in advanced safety needle integration and eco-friendly sterilization techniques. Our research indicates that companies providing customized procedure trays tailored for ambulatory surgical centers offer superior margin expansion opportunities compared to legacy commodity suppliers relying solely on standard hypodermic configurations.
Conclusion and Key Industry Takeaways
The market demonstrates undeniable resilience and lucrative expansion potential, projected to hit 4.50 Billion by 2033. Stakeholders must prioritize regulatory adaptability, material innovation, and strategic alignment with ambulatory care providers to capture maximum value in this evolving clinical landscape.
Research Methodology for Baseline Estimates
Our baseline estimates are rigorously triangulated by synthesizing customs trade registry data, primary qualitative interviews with C-suite medical device executives, and secondary macroeconomic indicators from global health organizations. This multi-tiered analytical approach ensures high-fidelity market sizing and accurate growth rate projections.
Scope of the Report and Coverage Parameters
This report covers global consumption, manufacturing dynamics, and regulatory landscapes across North America, Europe, Asia-Pacific, and Rest of the World. Limitations include the exclusion of reusable surgical instrumentation and non-sterile diagnostic sampling tools, keeping the primary focus strictly on disposable, pre-packaged puncture solutions.
Recent Developments and Strategic Industry Moves
Recent market activity is characterized by targeted acquisitions and portfolio expansions. Companies like Merit Medical Systems Inc. and Vygon S.A. have secured strategic partnerships to enhance their proprietary vascular catheter lines. Concurrently, regulatory approvals for novel safety needle mechanisms by firms such as TSK Laboratory International Co. Ltd. underscore ongoing technological advancement.